What is LTCG Tax on Mutual Funds?
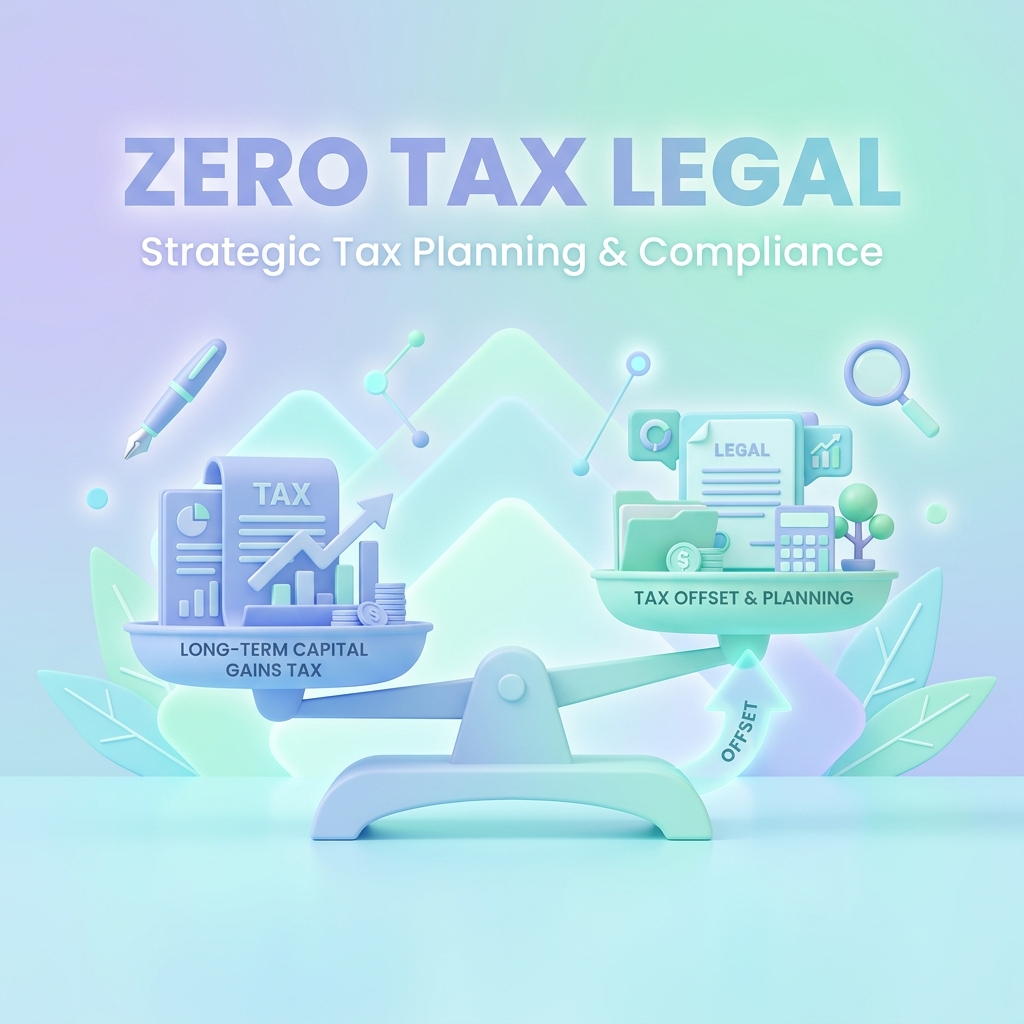
Long-Term Capital Gains (LTCG) tax is levied on profits from selling equity mutual funds held for more than 1 year. Post the 2024 Union Budget, the LTCG rate is 12.5%, with a ₹1.25 Lakh annual exemption. This is a key tax to plan around for your FIRE withdrawal strategy.
LTCG vs STCG: A Quick Reference
| Tax Type | Holding Period | Rate | Annual Exemption |
|---|---|---|---|
| LTCG (Long-Term Capital Gains) | More than 1 year | 12.5% | ₹1.25 Lakhs |
| STCG (Short-Term Capital Gains) | 1 year or less | 20% | None |
| Debt Fund Gains | Any period | As per income tax slab | None |
The Two Legal Strategies to Offset LTCG
Strategy 1: Annual Tax Harvesting (The ₹1.25L Loophole)
Every financial year, the government gives you a ₹1,25,000 LTCG exemption. If you do not proactively use it, you lose it.
Step-by-step:
- In late March every year, check your equity mutual fund unrealized gains
- Sell enough units to realize exactly ₹1.25 Lakhs in profit
- Pay zero tax (profit is under the exemption threshold)
- Immediately reinvest the proceeds in the same or equivalent fund
- Your new purchase price (cost basis) is now higher — future gains are lower
| Year | Cumulative Gain Harvested | Future Tax Saved (at 12.5%) |
|---|---|---|
| Year 1 | ₹1.25 Lakhs | ₹15,625 |
| Year 5 | ₹6.25 Lakhs | ₹78,125 |
| Year 10 | ₹12.5 Lakhs | ₹1,56,250 |
| Year 20 | ₹25 Lakhs | ₹3,12,500 |
Spousal Multiplier: If your spouse also has equity investments, harvest ₹2.5 Lakhs combined tax-free per year.
How much LTCG tax are you paying unnecessarily?
Model the exact LTCG impact of your retirement withdrawals and identify tax harvesting opportunities — automatically.
See a Live DemoStrategy 2: Tax-Loss Harvesting (Offset Gains with Losses)
If you hold any underperforming fund or stock in a loss position, do not hold it indefinitely hoping for recovery. Use it strategically.
Step-by-step:
- Identify assets showing a long-term capital loss
- Sell them to "crystallize" the loss
- Use this loss to offset your gains in the same year
- You can carry forward any unused loss for up to 8 assessment years
Example:
| Item | Amount |
|---|---|
| Realized LTCG from Nifty 50 fund | +₹4,00,000 |
| Less: ₹1.25L annual exemption | −₹1,25,000 |
| Taxable LTCG before loss harvesting | ₹2,75,000 |
| Realized LTCL from underperforming mid-cap fund | −₹2,00,000 |
| Net Taxable LTCG | ₹75,000 |
| LTCG Tax Payable (12.5%) | ₹9,375 |
| Without loss harvesting, tax would be | ₹34,375 |
Automate your tax harvesting math.
plannF's Tax Analytics module shows exactly which funds to sell, when, and how much to realize each year for optimal tax outcomes.
Start Your Free PlanFAQs
1. Is the LTCG exemption per person or per family?
It is per person. A married couple filing separate ITRs each gets a ₹1.25 Lakh exemption. This is the key advantage of spousal asset splitting — by keeping some investments in your spouse's name, your combined tax-free LTCG harvesting limit doubles to ₹2.5 Lakhs per year.
2. Can I offset equity LTCG with debt fund losses?
No. Capital gains and losses are offset within the same category. Long-term equity losses can only offset long-term equity gains. Short-term losses can offset both short-term and long-term gains from any source. Debt fund gains are taxed at your income tax slab rate, completely separately.
3. What is the wash sale rule in India — do I have to wait before buying back?
India does not have a formal "wash sale" rule (like the US 30-day waiting period). You can sell a fund unit on March 31st and buy back on April 1st. The government has not prohibited this. This is why annual tax harvesting works so effectively in India.
4. How does LTCG tax impact my Safe Withdrawal Rate in early retirement?
Significantly. If you plan to withdraw ₹9 Lakhs/year from equity funds, and your entire gain is taxable, you pay ₹96,875 in LTCG tax. But with proper tax harvesting and spousal splitting, you could reduce this to ₹0. This difference of ~₹1 Lakh/year compounded over 30 years is enormous. See our complete guide to tax harvesting.
5. How does plannF help with LTCG tax optimization?
plannF's Tax Analytics module calculates your exact LTCG liability each year based on your projected withdrawals. It identifies the optimal sell amount for annual tax harvesting, models the impact of spousal splitting, and shows your true post-tax cash flow — so you never accidentally overpay taxes in retirement.