The Fear of the Crash
The single biggest fear for any Indian early retiree is a market crash. You spend 20 years building a ₹5 Crore portfolio, you quit your job, and six months later, the Nifty 50 drops by 35%.
If your money is entirely in equity, you are now forced to sell units at a massive loss just to pay your electricity bill. This permanent destruction of principal is known as Sequence of Returns Risk.
The most robust, time-tested defense against this risk is The Bucket Strategy.
What is the Bucket Strategy?
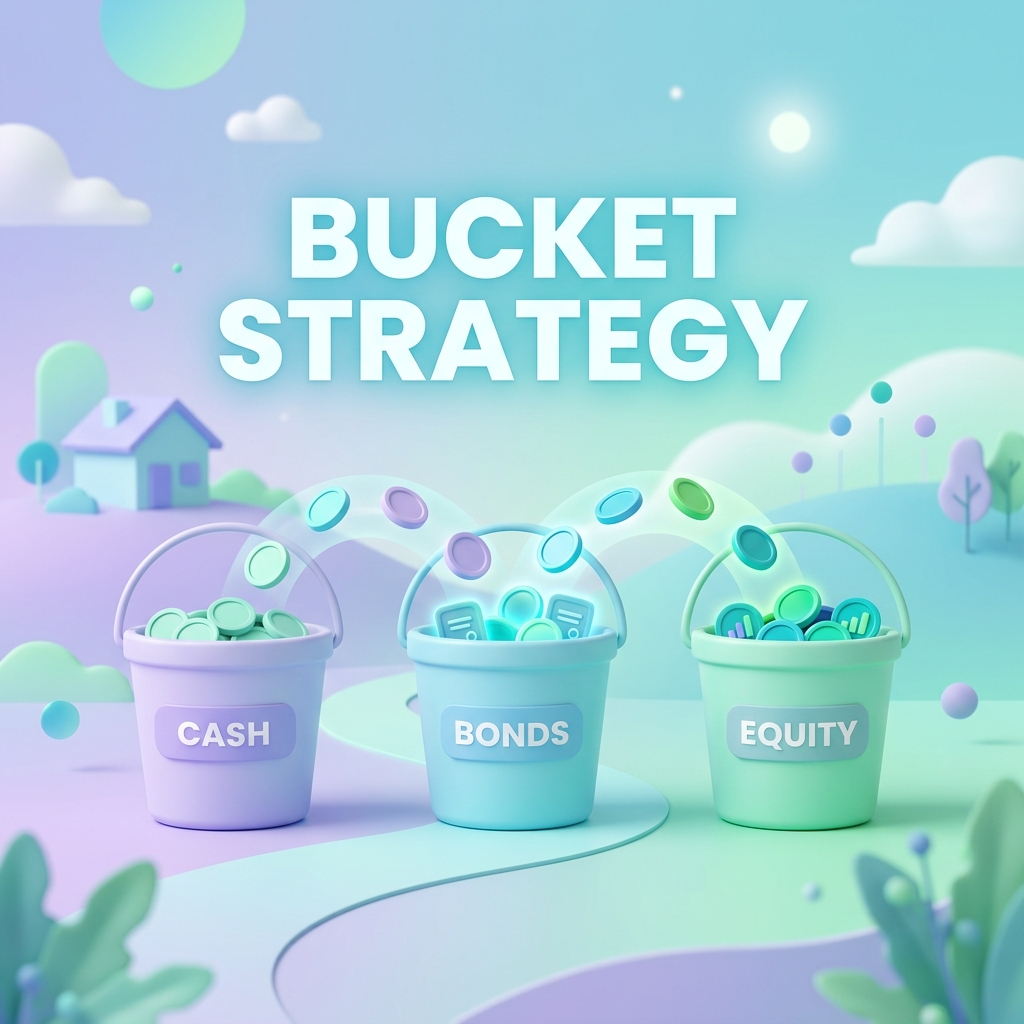
The Bucket Strategy is a portfolio withdrawal system that segments your retirement corpus into distinct "buckets" based on when you need the money. Short-term buckets hold extremely safe, liquid assets, while long-term buckets hold volatile, high-growth assets.
This ensures you are never forced to sell equity during a market panic.
How to Build Your Buckets in India
For a typical early retiree in India, a 3-Bucket system is mathematically optimal.
Bucket 1: The "Now" Bucket (Years 1 to 3)
- Time Horizon: Money you need in the next 0 to 36 months.
- Goal: Absolute capital protection and instant liquidity.
- Asset Allocation: 100% Cash Equivalents.
- Indian Vehicles: Arbitrage Funds, Liquid Mutual Funds, High-Yield Savings Accounts, and short-term Fixed Deposits.
- Action: You live entirely out of this bucket. You sell these units every month to fund your life. If the stock market drops 40% tomorrow, your life doesn't change because your grocery money is sitting in a safe Arbitrage fund.
Bucket 2: The "Soon" Bucket (Years 4 to 10)
- Time Horizon: Money you need in the medium term.
- Goal: Beat inflation with moderate safety.
- Asset Allocation: 100% Debt and Hybrid assets.
- Indian Vehicles: EPF (if accessible), PPF, Corporate Bond Funds, Balanced Advantage Funds (BAFs), and Sovereign Gold Bonds (SGBs).
- Action: As Bucket 1 depletes, you slowly sell assets from Bucket 2 to refill it.
Bucket 3: The "Later" Bucket (Years 11+)
- Time Horizon: Money you won't touch for over a decade.
- Goal: Maximum long-term growth to outpace 14% healthcare inflation.
- Asset Allocation: 100% Equity.
- Indian Vehicles: Nifty 50 Index Funds (like those tracking the NSE indices), Flexi-Cap Funds, Mid-Cap Index Funds.
- Action: This is your engine. You leave this bucket alone to compound wildly. In years when the market is up significantly, you skim the profits from this bucket to refill Bucket 2 and Bucket 1.
The Refill Mechanism (How it actually works)
The beauty of the Bucket Strategy is the refill rules.
Rule 1: In a Bull Market The Nifty 50 goes up 18%. Your Equity (Bucket 3) swells. You harvest ₹1.25 Lakhs of tax-free LTCG from Bucket 3 and use it to replenish the cash you spent from Bucket 1.
Rule 2: In a Bear Market The Nifty 50 crashes by 25%. You do absolutely nothing to Bucket 3. You let it recover. You continue spending from Bucket 1. Since Bucket 1 holds 3 years of cash, you can comfortably wait out the 18 to 24 months it typically takes for the Indian equity market to recover from a recession.
Simulate Your Buckets
Managing buckets manually requires discipline. If you want to see how a 3-bucket system survives historical market crashes in India, run your portfolio through our Tax Analytics & Simulator.
FAQs
1. How many buckets are ideal for Indian retirees?
A 3-bucket system is optimal for most. Bucket 1 (0-3 years) for immediate cash, Bucket 2 (4-10 years) for medium-term debt, and Bucket 3 (11+ years) for long-term equity growth.
2. Can I use Fixed Deposits for Bucket 1?
Yes, short-term FDs are extremely safe and work well for Bucket 1. However, Arbitrage Funds are often preferred by high-net-worth retirees due to their favorable equity taxation.
3. When exactly should I refill Bucket 1?
Most retirees use an annual refill strategy. Once a year (often in March to harvest tax), you assess the market. If Bucket 3 (Equity) is up, you sell from there. If it's down, you sell from Bucket 2 (Debt).
4. What happens if both Equity and Debt crash at the same time?
While rare, if both markets crash simultaneously, Bucket 1 provides a 3-year cash buffer. You simply live off Bucket 1 without touching your volatile assets until they recover.
5. How does plannF help with the Bucket Strategy?
plannF automatically simulates your portfolio across different asset classes, allowing you to model withdrawal sequences that mimic the bucket strategy and protect you from Sequence of Returns Risk.