One Acronym, Completely Different Lives
When you tell someone you are planning for FIRE (Financial Independence, Retire Early), they usually picture one of two extremes:
- Moving to a village, growing vegetables, and living like a monk.
- Sipping cocktails on a Goa beach with infinite money.
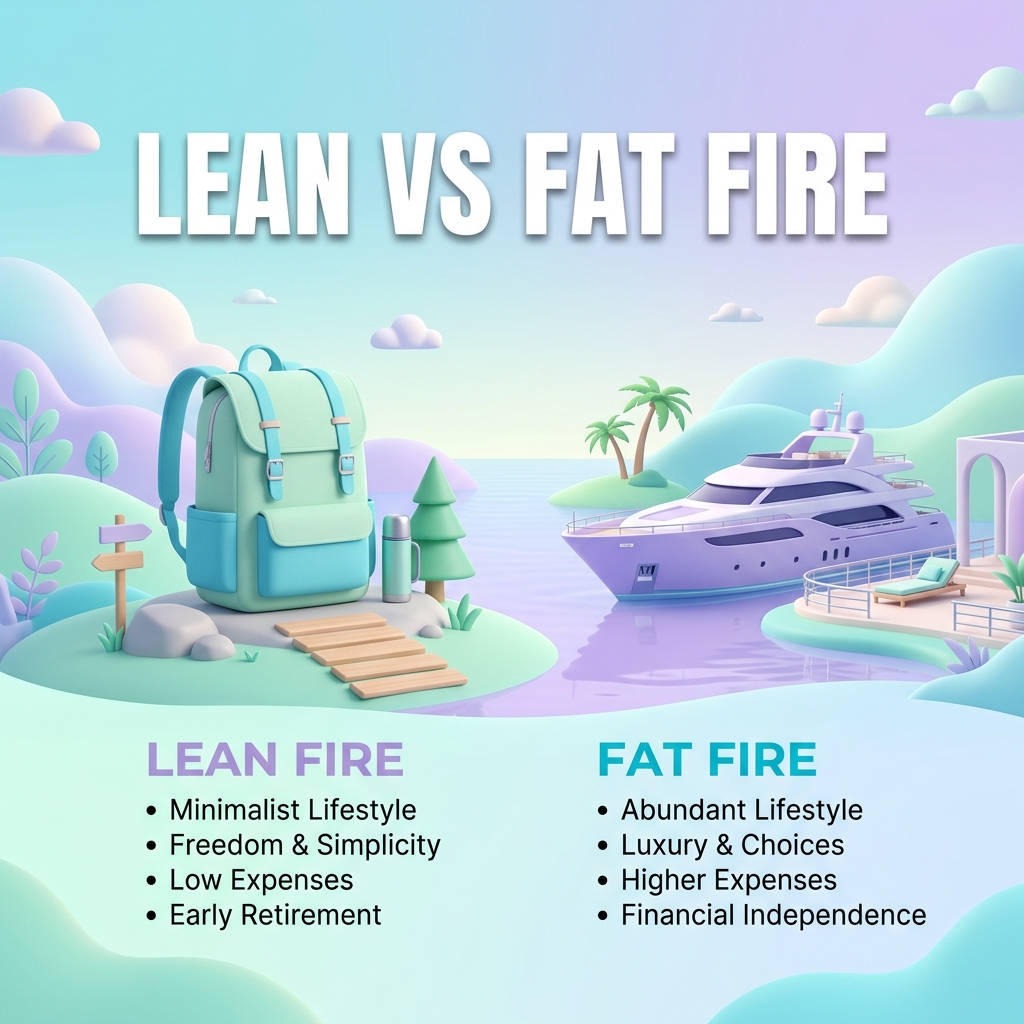
In reality, FIRE is a spectrum. Depending on your desired lifestyle, the corpus you need can range from ₹1.5 Crores to over ₹10 Crores. The three main points on this spectrum are Lean FIRE, Chubby FIRE, and Fat FIRE.
The Complete FIRE Spectrum: India 2026
| FIRE Type | Monthly Expenses | Corpus Needed | SWR Used | Typical Profile |
|---|---|---|---|---|
| Lean FIRE | ₹40,000 – ₹60,000 | ₹1.6 – ₹2.4 Crore | 3.0% | Tier-2 city, owned home, frugal lifestyle |
| Regular FIRE | ₹70,000 – ₹1 Lakh | ₹2.8 – ₹4 Crore | 3.0% | Metro with owned home, moderate lifestyle |
| Chubby FIRE | ₹1 – ₹1.5 Lakhs | ₹4 – ₹6 Crore | 3.0% | Metro life, annual international vacation, premium insurance |
| Fat FIRE | ₹2.5 – ₹5 Lakhs+ | ₹10 – ₹20 Crore | 3.0% | Absolute luxury, no budget anxiety, multiple properties |
Corpus calculated using 3.0% SWR (safe for India's 6-7% inflation environment). See our SWR guide for details.
Which FIRE type fits your lifestyle?
Enter your target monthly expenses into the plannF FIRE Calculator and see exactly how many years to your target corpus.
See a Live DemoWhat is Lean FIRE?
Lean FIRE is achieving financial independence by deliberately minimizing living expenses to a comfortable baseline. It requires a smaller corpus but demands geographic optimization and spending discipline.
Lean FIRE Budget Breakdown (₹50,000/month example)
| Category | Monthly Budget |
|---|---|
| Groceries & cooking at home | ₹8,000 |
| Utilities (electricity, internet, water) | ₹3,000 |
| Health insurance (self + spouse) | ₹5,000 |
| Transport (hatchback EMI or 2-wheeler) | ₹5,000 |
| Entertainment & dining out | ₹4,000 |
| Domestic travel (2 trips/year) | ₹4,000 |
| Miscellaneous | ₹5,000 |
| Emergency buffer | ₹16,000 |
| Total | ₹50,000 |
Corpus Required: ₹50,000 × 12 ÷ 3% = ₹2 Crores
Best suited for: Tier-2 or Tier-3 cities (Mysore, Coimbatore, Indore, Nashik) with a fully paid-off home.
The advantage: Speed. A disciplined high-earner can hit Lean FIRE by age 35. The risk: Very little buffer for unexpected expenses, luxury, or severe inflation spikes.
What is Fat FIRE?
Fat FIRE is achieving financial independence with a corpus large enough to fund a highly luxurious lifestyle without ever thinking about budgets.
Fat FIRE Budget Breakdown (₹2.5 Lakhs/month example)
| Category | Monthly Budget |
|---|---|
| Premium apartment maintenance or rent | ₹50,000 |
| Groceries + gourmet dining (4x/week) | ₹30,000 |
| Premium health insurance (family floater + super top-up) | ₹15,000 |
| Luxury vehicle (EMI or depreciation allowance) | ₹30,000 |
| International travel (3-4 trips/year) | ₹40,000 |
| Lifestyle (premium subscriptions, events, gifts) | ₹20,000 |
| Children's private school fees | ₹30,000 |
| Miscellaneous + emergency buffer | ₹35,000 |
| Total | ₹2,50,000 |
Corpus Required: ₹2.5L × 12 ÷ 3% = ₹10 Crores
Best suited for: Top-tier metros with years of high savings rate or a business exit event.
How many extra years does Fat FIRE cost vs Lean FIRE?
Run both scenarios side by side in plannF and see the exact year difference — so you can make an informed lifestyle trade-off.
Start Your Free PlanThe Middle Ground: Chubby FIRE
For most Indian IT or Finance professionals, the sweet spot is Chubby FIRE: ₹1 to ₹1.5 Lakhs/month, requiring ₹4–6 Crores.
This allows a comfortable upper-middle-class metro life — premium healthcare, occasional international travel, no EMI anxiety — while being an achievable target for most high-income professionals by their mid-40s. See our articles on ₹5 Crore retirement for the specific math.
Which Path Is Right for You?
The right FIRE type depends on the intersection of:
- Your current savings rate — how fast you can accumulate
- Your lifestyle non-negotiables — what would feel like genuine deprivation
- Your geographic flexibility — are you willing to relocate to a Tier-2 city?
You cannot decide this in a vacuum. You need to simulate both scenarios side-by-side to see how many extra years of work a "Fat" lifestyle costs you.
Map your exact FIRE timeline.
Enter your current corpus, savings rate, and target lifestyle into the plannF FIRE Calculator to see your personalized retirement timeline.
Launch the FIRE CalculatorFAQs
1. Is Lean FIRE sustainable in India with rising healthcare costs?
Lean FIRE is sustainable only if you own your home outright (eliminating rent), have comprehensive health insurance (Base + Super Top-Up), and live in a city where ₹40,000-50,000 genuinely covers a good lifestyle. The biggest risk is healthcare inflation at 12-14% eroding your medical budget over 30+ years.
2. Can I start with Lean FIRE and upgrade to Chubby FIRE later?
Yes — this is actually the recommended strategy for many people. Start Lean FIRE early at age 38-40 with a ₹2 Crore corpus. Live lean for 3-5 years while your corpus continues compounding. By 43-45, your corpus may have grown to ₹4 Crores, unlocking Chubby FIRE without any additional work.
3. Is Fat FIRE only possible for people with high salaries?
Not necessarily. Many Fat FIRE stories in India involve business exits, ESOP liquidation events, or selling a startup. For salaried professionals, Fat FIRE typically requires either a ₹30 Lakh+ annual income sustained for 15+ years, or extraordinary luck with equity (ESOP/startup equity). At a ₹20 Lakh income with 50% savings rate, you would reach Fat FIRE in approximately 25-28 years.
4. What happens to Lean FIRE people during a major market crash?
This is the critical risk of Lean FIRE — there is no lifestyle buffer. If the market crashes 50% and your ₹2 Crore corpus drops to ₹1 Crore, you would need to re-enter the workforce or drastically cut expenses. This is why a Cash Buffer of 2-3 years and a Bond Tent strategy are non-negotiable for Lean FIRE retirees.
5. How does plannF help compare Lean vs Fat FIRE scenarios?
plannF allows you to create and save multiple retirement scenarios. You can build a "Lean FIRE at 40" scenario and a "Chubby FIRE at 47" scenario side-by-side — with different expense targets, corpus targets, and timelines. The visual year-by-year comparison makes the trade-off tangible and helps you find the exact lifestyle-vs-years-of-work balance that is right for you.